Carrying credit card debt can lead to a cycle of growing interest charges. This guide explains practical steps to reduce or eliminate interest by prioritizing payments, optimizing existing tools, and establishing a clear plan. The focus is on actionable, beginner-friendly strategies that work with common personal finance tools.
Quick Answer
Pay more than the minimum each month until balance is zero and consider transferring balances to a 0% APR offer if available. Use a structured plan with reliable tools to track progress and stay on target.
What You’ll Need
- credit card payoff calculator
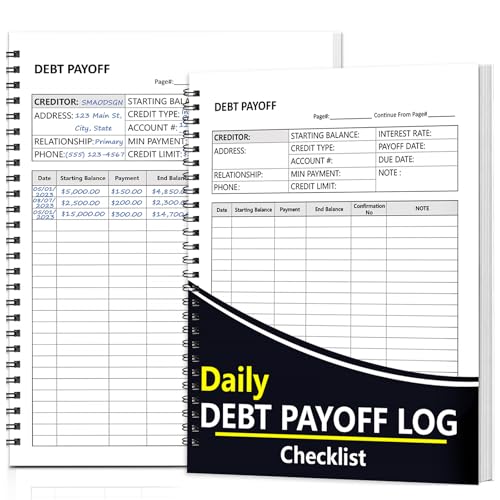
- debt payoff planner notebook
- credit card balance tracker journal
- budget planner binder personal finance
- debt reduction strategy workbook


Before You Start
Assess the current situation: total card balances, interest rates, and minimum payments. Gather all statements and know the exact APRs. Safety note: avoid new debt while paying down existing balances. Time estimates vary, but most payoff plans take several months to over a year depending on balance and payment amount. If you’re juggling multiple cards, prioritize the one with the highest APR first, then tackle others.
Step-By-Step: How To Stop Paying Credit Card Interest
- Compile all balances and APRs in one place using a payoff calculator for a clear payoff date.
- Choose a payoff strategy, such as the Snowball (smallest balance first) or Avalanche (highest APR first), and commit to it.
- Set a realistic monthly payment target that exceeds the total minimums and aligns with your budget.
- Make the target payment as soon as your paycheck arrives to maximize the time your money has to work against interest.
- Consolidate or transfer balances only if a confirmed 0% or low-interest offer is available and lasting long enough to save interest.
- Track progress weekly with a credit card balance tracker journal to stay motivated and observe interest decline.
- Automate payments where possible to avoid missing due dates and triggering late fees or higher rates.
- Reevaluate monthly spending and trim discretionary expenses to free funds for debt payoff.
- Review statements for any card fees or penalties and dispute any errors promptly to avoid inflated costs.
- Once a card is paid off, apply the freed funds to the next card or the highest APR balance to accelerate relief.
- Keep open lines of communication with lenders if financial hardship occurs; request payment arrangements if needed.
- Maintain momentum by updating your payoff plan with new numbers and revising targets as balances drop.
Troubleshooting
| Symptom | Likely Cause | Fix | Prevention |
|---|---|---|---|
| Payments not reducing balance as expected | Underestimated fees or new charges | Recalculate with payoff calculator after every statement | Track charges weekly; set alerts |
| Interest continues after payoff date | Assuming payoff dates without considering variable rates | Re-run plan with current APRs | Lock in a payoff window and avoid new debt |
| Minimum payment keeps reappearing as large | Balance increased by new purchases | Pause new purchases; use a separate card for essentials | Use budget to prevent new debt |
| Balance transfers rejected | Credit limits or timing issues | Ask for higher limit or wait for a promo window | Monitor offers and timing |
Common Mistakes
- Focusing on paying one card while ignoring higher-APR balances elsewhere
- Making only the minimum payment due to cash flow issues
- Opening new credit lines while trying to pay down debt
- Ignoring fees and penalties that keep balances rising
Tips For Best Results
- Automate payments for at least the minimum due plus extra toward the target card
- Use a payoff calculator to model different payment amounts and outcomes
- Combine debt payoff with a tight monthly budget to free up more funds
- Consider a balance transfer only if the long-term savings are clear and protected by a plan
- Keep emergency savings intact to avoid new debt if unexpected expenses arise
Call A Professional
Seek professional help if debt becomes unmanageable or you face wage garnishments, lawsuits, or persistent collections actions. Signs to contact a pro include missed payments due to income loss, inability to budget, or repeated failed payoff attempts despite consistent effort.
FAQ
Can I really eliminate credit card interest quickly?
Interest can be reduced significantly by paying more than the minimum and prioritizing high-APR balances, though the timeline depends on balance size and rate.
Is a balance transfer worth it?
Only if the transfer offers a long 0% APR period and you can pay off the balance before the promo ends.
Should I close old cards after paying them off?
Closing may impact credit utilization and score; consider keeping them open with zero balances unless fees apply.
What if I miss a payment?
Pay as soon as possible and contact the issuer to minimize penalties and preserve the payoff plan.
How often should I review my payoff plan?
Review monthly after statements arrive, and adjust if APRs or balances change.
What tools help most with this process?
Payoff calculators, debt payoff planners, balance trackers, and budget binders are typically the most effective supports.
What is the fastest way to reduce interest charges?
Accelerate payments toward the highest-APR balance and avoid new purchases on that card.
Buying Guide
When choosing tools to support credit card payoff efforts, consider factors such as size, ease of use, and compatibility with your budgeting style. A robust budget planner binder personal finance can centralize tracking, while a credit card payoff calculator helps forecast outcomes. For those who prefer tangible planning, a debt payoff planner notebook or credit card balance tracker journal provides a dedicated place to log progress. Evaluate how debt reduction strategy workbook content aligns with your strategy, whether you focus on Snowball or Avalanche methods. Look for tools that offer clear instruction, printable sheets, and secure data handling. Consider whether you want digital access, physical copies, or a hybrid setup to maximize consistency and motivation.