Sallie Mae loans, including private student loans, can feel burdensome when monthly payments stretch over many years. This guide offers practical, step-by-step methods to reduce or eliminate Sallie Mae debt using widely available tools and careful budgeting. The focus is on proven payoff strategies and clear actions that Americans can implement today.
Readers will find a structured approach to analyze loan terms, create a realistic payoff plan, and monitor progress. The steps emphasize responsible budgeting, disciplined repayment, and avoiding common pitfalls that slow progress or increase total interest over time.
Quick Answer
Prioritize high-interest balances, then accelerate payments with a clear plan. Use a structured payoff workflow, track progress in a debt payoff planner, and consider refinements such as refinancing or consolidation only after evaluating costs and benefits with a financial professional.
What You’ll Need
- Debt payoff planner notebook
- Amortization schedule calculator for loans
- Student loan payoff workbook
- Budget planner for debt payoff binder
- Financial organizer debt reduction planner
- Regular access to online loan statements
- Banking tools for automatic or accelerated payments

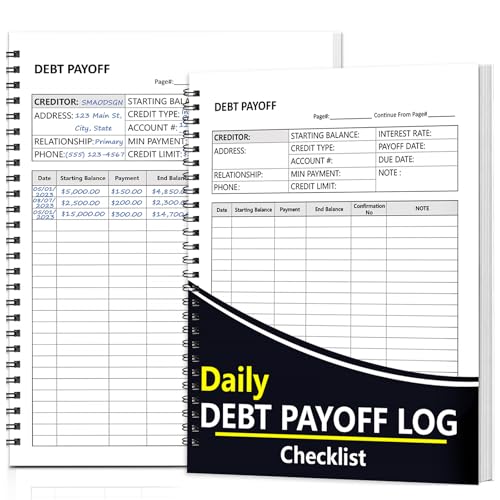
Before You Start
Before tackling Sallie Mae debts, collect all loan documents, including notices from lenders, current balances, interest rates, and the loan servicer contact information. Verify which loans are private Sallie Mae products and which may be federal, as repayment options differ. Important cautions include confirming the total number of loans, their current interest rates, and any deferment or forbearance options that might apply in hardship situations.
Time estimates vary, but a thorough planning phase typically takes 1–2 hours to assemble documents and set initial targets. A realistic monthly budget that accounts for essential living costs should be prepared. Safety notes include protecting personal data during online account access and avoiding high-fee debt relief offers.
Step-By-Step: How To Pay Off Sallie Mae Loans
- Identify all private Sallie Mae loans and separate them from any federal loans. List each loan’s balance, interest rate, and minimum monthly payment.
- Choose a primary payoff strategy such as the avalanche method (highest interest first) or the snowball method (smallest balance first). The avalanche method typically saves more interest over time.
- Create a target payoff date based on current budgets and available extra funds. Set quarterly milestones to stay motivated and track progress.
- Build a monthly budget using a debt payoff binder and budget planner. Identify discretionary expenses that can be redirected toward loan payments.
- Allocate extra payments strategically to the highest-interest loan first, while continuing minimums on all other loans. Document any payment allocation in the payoff notebook.
- Monitor and update the amortization schedule regularly. Use the amortization schedule calculator to project payoff timelines with accelerated payments.
- Automate payments where possible to reduce the risk of late fees and missed opportunities for interest savings. If allowed, enable biweekly payment schedules to shorten the amortization period.
- Reassess periodically for opportunities to save, such as refinancing options or lender-specific payoff plans. Consult a financial advisor before making major changes.
Troubleshooting
| Symptom | Likely Cause | Fix | Prevention |
|---|---|---|---|
| Payments not reducing principal fast | Allocations to principal are too small or misapplied | Double-check loan allocation and ensure extra payments go toward principal | Review payment instructions with servicer regularly |
| Interest rate higher than expected | Loan type or misclassification | Confirm with servicer; verify if rate is fixed vs variable | Document rate terms and monitor notices |
| Confusing payoff timeline | Inaccurate amortization projection | Recalculate with an up-to-date schedule | Update calculator whenever balances change |
| Payment reminders causing stress | Overwhelming monthly dues | Switch to a sustainable payment plan; set alerts only for essential dates | Maintain a realistic budget buffer |
Common Mistakes
- Focusing on small balance loans at the expense of higher-interest ones
- Missing minimum payments on any loan, which can trigger penalties
- Overcommitting time or money, leading to burnout and reduced consistency
- Not updating the payoff plan after life changes (income, expenses, or interest rate changes)
- Neglecting to confirm that extra payments are applied to principal
Tips For Best Results
- Keep all payoff materials organized in a dedicated binder or digital folder to track progress over time.
- Use the amortization schedule calculator to simulate different payment scenarios and choose the most effective one.
- Set quarterly reviews to adjust contributions if income rises or expenses fall.
- Automate at least the minimum payments to prevent missed payments, then add extra funds as available.
- Consider refinancing only after evaluating total costs, including any loss of benefits or protections.
Call A Professional
Seek professional guidance if any of the following occur: multiple loans with complex terms, delinquency risk, or inability to make minimum payments. A financial advisor can help evaluate consolidation or refinancing options, but readers should beware of high-fee, non-fair-market products. If legal actions or threats of wage garnishment arise, contact a consumer attorney or nonprofit credit counselor for safe, unbiased advice.
FAQ
Can I payoff Sallie Mae private loans faster without refinancing?
Yes, by applying extra payments to the highest-interest loan and maintaining timely minimums on the rest, especially when using a structured payoff plan.
Is it better to refinance private Sallie Mae loans?
Refinancing can reduce interest or simplify payments, but it may remove borrower protections and incentives tied to federal options. Evaluate total cost and benefits with care.
How do I track progress effectively?
Use a debt payoff notebook or workbook and an amortization calculator to compare projected vs. actual payoff timelines.
What if I face a financial setback?
Communicate with the loan servicer early to discuss forbearance, deferment, or adjusted repayment plans; adjust your budget accordingly.
Are biweekly payments beneficial?
Biweekly payments can shorten the loan term and reduce interest, but only if the lender supports such a schedule and fees are clear.
What if I have both private and federal loans?
Handle federal loans with federal options first (Income-Driven Repayment, PSLF when eligible). Private loans require separate strategies and careful consideration of credit implications.
Buying Guide
When selecting tools to manage Sallie Mae debt, consider key buying factors that support a clear payoff path:
- <bSize and scope: Choose planners and notebooks that accommodate multiple loans and long-term tracking without becoming bulky.
- <bNoise level: Digital tools offer quiet operation and instant updates, while printed binders provide physical note-taking benefits.
- <bEnergy efficiency: If using digital devices for payoff work, prefer energy-efficient devices or battery-powered options for long sessions.
- <bControls and usability: Look for intuitive interfaces in calculators and trackers; a well-organized workbook reduces cognitive load.
- <bPlacement and accessibility: Keep materials in a central, accessible location—home office, desk drawer, or cloud-based folder.
- <bCompatibility: Ensure tools work with common formats (PDF, CSV, or printable worksheets) for easy data import/export.
- <bCost: Prioritize affordable, proven planners and calculators; avoid high-pressure upsells.
- <bSupport and updates: Prefer products with clear instructions, templates, and optional updates or customer support.